Categories
Mortgage Calculator, How to Calculate Mortgage, Choosing a Realtor, Choosing an Advisor, Home Buyers, Home Buying, Real Estate Education, Real Estate Professional, Selling and Buying in Utah, VA Home LoanPublished October 21, 2026
How to Calculate Your Monthly Mortgage Payment in Utah
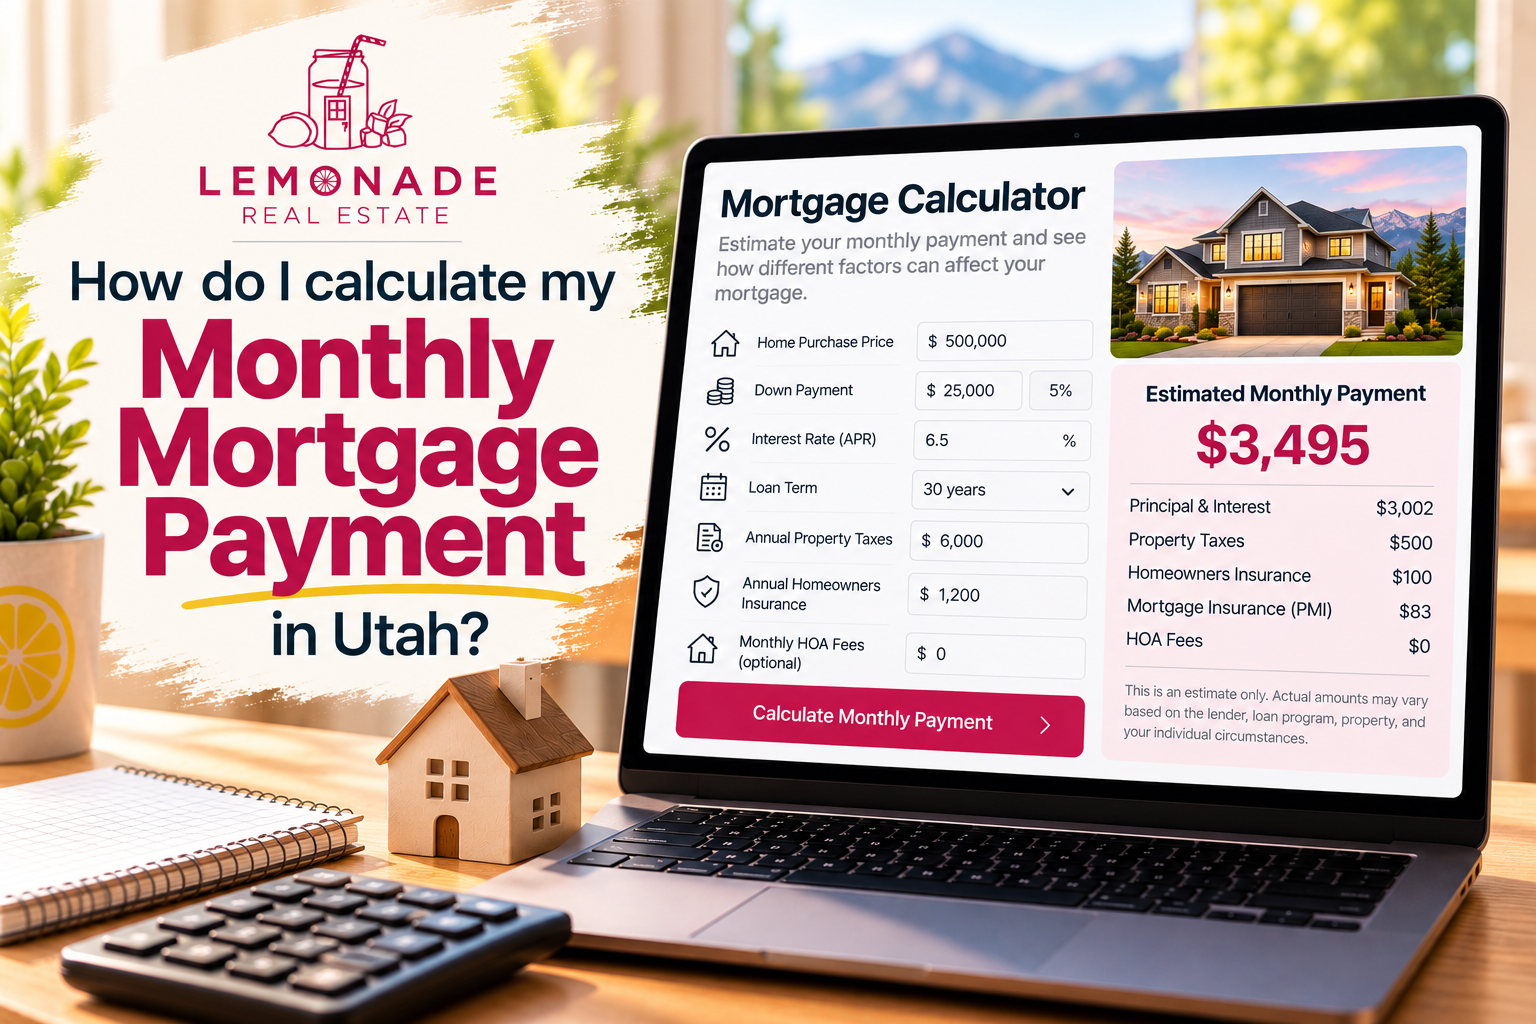
How Do I Calculate My Monthly Mortgage Payment in Utah?
One of the most important questions to ask when purchasing a home is, "What will my monthly mortgage payment be?" While the purchase price is certainly important, your monthly payment is determined by several different variables, and even small adjustments can make a significant difference in what you pay each month.
At Lemonade Real Estate, I encourage buyers to look beyond the sales price and understand the full financial picture before purchasing a home. The goal isn't simply to qualify for a mortgage. It's to find a great property that meets your family's needs while making the most of your available financing options.
What Goes Into a Monthly Mortgage Payment?
There are several mortgage calculators available online, but one resource I recommend is the mortgage calculator on UtahRealEstate.com.
When calculating your estimated monthly payment, you'll want to consider the following variables:
- Home purchase price: The agreed-upon sales price of the property.
- Annual interest rate: The interest rate charged by your mortgage lender.
- Loan term: The length of your mortgage, commonly 15 or 30 years.
- Down payment: The amount of money you're contributing toward the purchase upfront.
- Private mortgage insurance (PMI): Typically required on conventional loans with less than 20% down. Certain loan programs, including VA loans, do not require monthly PMI.
- Property taxes: The estimated annual property taxes divided into monthly payments.
- Homeowners insurance: The estimated annual cost of insuring your property.
- HOA fees: Any monthly or periodic homeowners association dues.
- Additional expenses: Other applicable monthly housing costs, such as certain special assessments, loan-program fees and even a second mortgage.
Together, these expenses help estimate your total monthly housing payment, often referred to as principal, interest, taxes, and insurance (PITI), plus any applicable mortgage insurance and HOA fees.
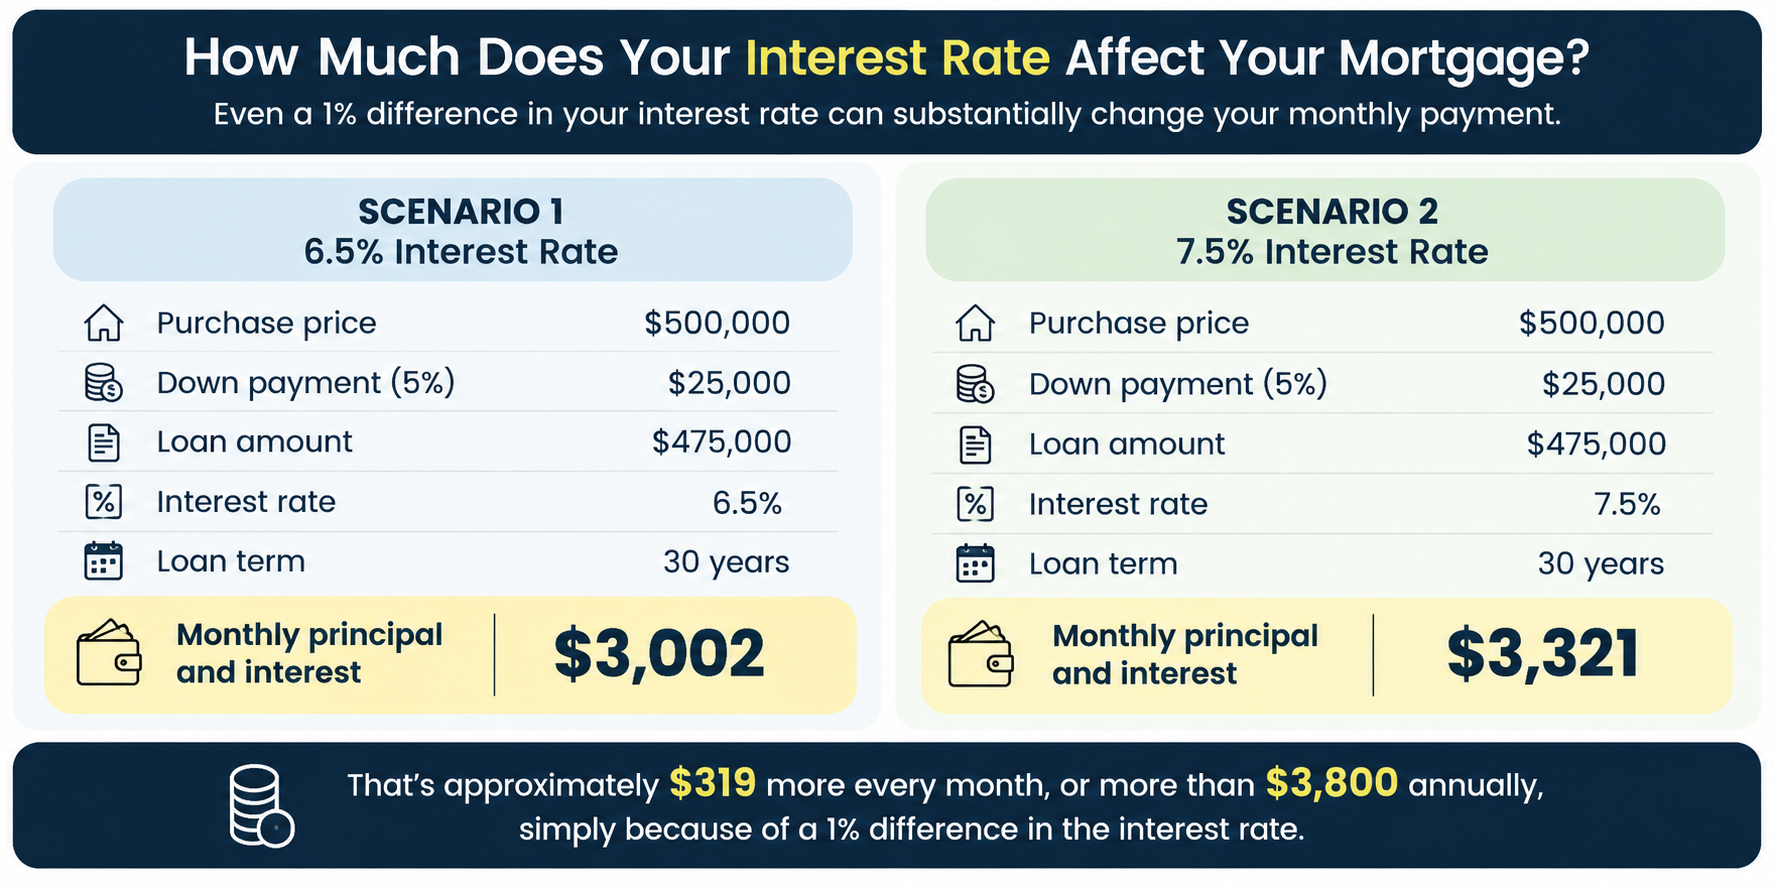
(Property taxes, homeowners insurance, mortgage insurance, and HOA fees would be additional expenses.)
Focus on the Variables You Can Control
While mortgage rates and housing market conditions aren't entirely within your control, that doesn't mean you don't have options. For example, if interest rates are elevated, you might consider negotiating a lower purchase price, increasing your down payment if financially appropriate, or exploring available interest-rate buydown options with your lender. You may also find that purchasing a slightly less expensive home gives you considerably more financial flexibility.
I also encourage buyers to consider the long-term benefits of purchasing at a comfortable price. If mortgage rates decrease in the future, refinancing may provide an opportunity to lower your monthly payment, although refinancing is never guaranteed and comes with its own costs and qualification requirements. The important thing is that you can potentially refinance your interest rate, but you cannot go back and renegotiate the original purchase price after closing. That's why making a financially responsible purchase today is so important.
Every Buyer's Mortgage Situation Is Different
One of the most important things to understand about mortgage calculators is that they're a starting point, not a final answer. Your actual payment can vary considerably depending on the type of loan you qualify for, your financial circumstances, and the benefits or programs available to you.
For example, eligible military veterans may qualify for a VA home loan with no down payment and no monthly private mortgage insurance. Veterans with qualifying service-connected disabilities may also be exempt from the VA funding fee, potentially reducing their upfront borrowing costs. Here in Utah, qualifying disabled veterans may also be eligible for a property tax abatement, which can further reduce their overall housing expenses. At Lemonade Real Estate, we help our veteran clients navigate these opportunities, including assisting them through the county application process for available disabled veteran property tax benefits. Eligibility and savings depend on individual circumstances and applicable requirements.
The reality is that there's no one-size-fits-all mortgage strategy. Every buyer has a different financial picture, and the right loan program, down payment, purchase price, and available benefits can make a meaningful difference in what homeownership costs.
If you're getting closer to purchasing a home in Utah, I encourage you to contact Lemonade Real Estate. Our team would love to walk you through potential home options, connect you with reputable mortgage lenders, and help you understand which factors may influence your monthly payment. The earlier we begin planning, the better positioned you'll be to make an informed decision when the right home becomes available.
🍋 Lemonade Real Estate | Sweetly Guiding You Home
Abe Mardanlou, Owner and Associate Broker
801.664.1546
https://www.lemonaderealestate.co
or another way